
Home Insurance in 2026: What Tri-Valley Buyers and Sellers Need to Know
Veronica Peter October 1, 2026
Veronica Peter October 1, 2026
Disclaimer: This post is for general information only and is not insurance advice. Rates, coverage options, and regulations change. Consult a licensed insurance professional for guidance on your specific property.
A few years ago, homeowners insurance was an afterthought in most Tri-Valley transactions. You picked a carrier, got a quote, and moved on. That's no longer the case. California's insurance market has changed dramatically, and in 2026 insurance can affect a buyer's monthly budget, a lender's approval, and occasionally whether a deal closes at all.
Here's what buyers and sellers in Livermore, Pleasanton, Danville, Dublin, and San Ramon should know heading into the fall and winter.
Over the past several years, many major insurers reduced or paused writing new policies in California, particularly in areas with elevated wildfire risk. As a result, more homeowners have turned to the California FAIR Plan, the state's insurer of last resort.
Two developments are especially relevant this fall:
Much of the Tri-Valley sits near open space: the hills of South Livermore, the ridgelines around Pleasanton and Danville, and the open grasslands bordering parts of San Ramon and Dublin. Homes near that wildland interface can fall into higher Fire Hazard Severity Zones, and CAL FIRE updated its hazard maps in 2025, which moved some properties into new designations.
That doesn't mean these homes are uninsurable. It means insurance takes more planning than it used to, and the cost can vary significantly from one street to the next.
Your lender will require proof of homeowners insurance before closing. If you wait until the last week of escrow to shop for coverage, you risk delays or unwelcome surprises. Here's a better approach:
If your home is in a higher fire hazard zone, buyers and their agents will ask about insurance. Answering that question before it comes up can keep your sale on track.
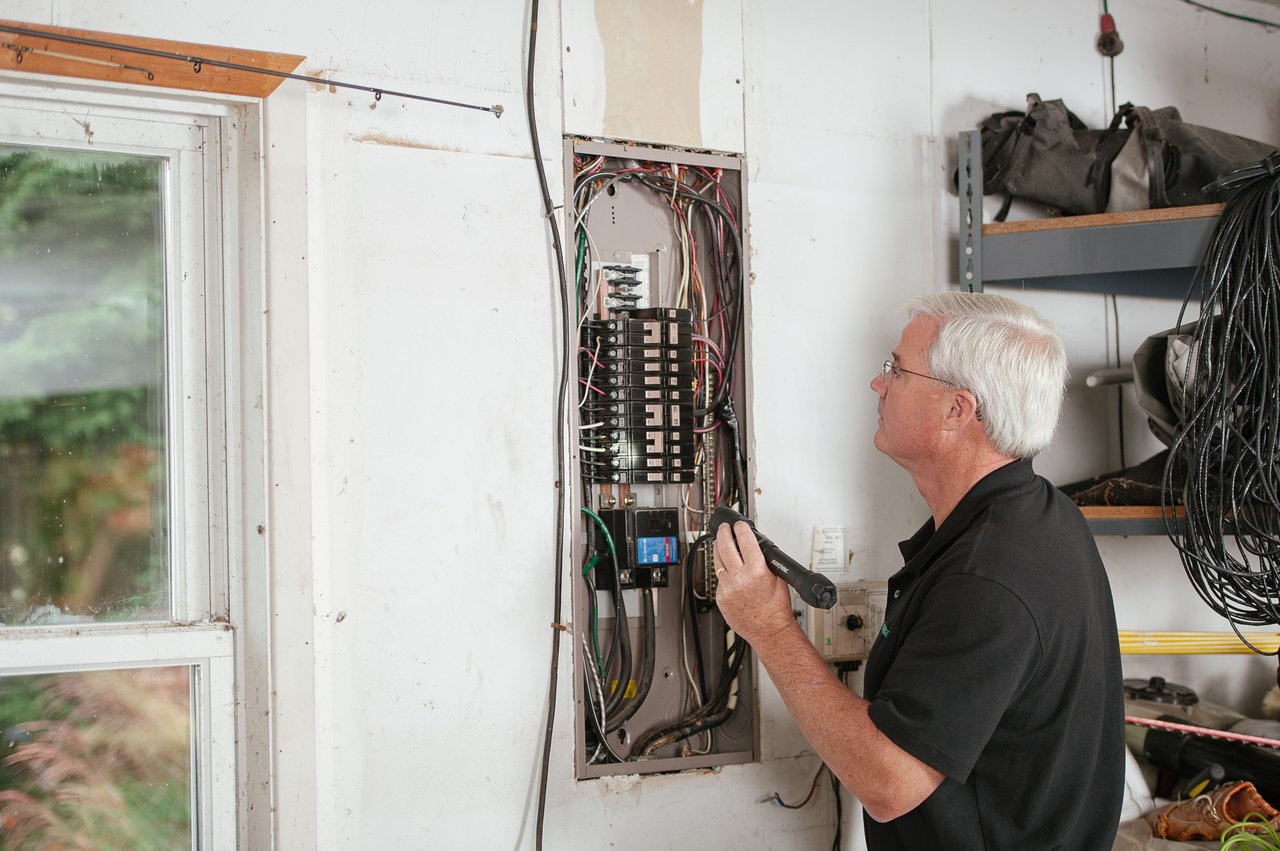
Whether you're buying, selling, or staying put, these improvements can reduce risk and may help with coverage:
Fall is also the start of the rainy season, which is a good time to check your roof and drainage. See What the Rainy Season Reveals.
Insurance is now a real part of the Tri-Valley buying and selling process, not a formality. Buyers who shop for coverage early avoid last-minute surprises, and sellers who document their home's insurability give buyers confidence. If you're considering a home near open space or preparing to list one, I can connect you with independent insurance brokers who know our area and help you plan around coverage from day one.
Disclaimer: This post is for general information only and is not insurance advice. Rates, coverage options, and regulations change. Consult a licensed insurance professional for guidance on your specific property.
It isn't just earthquakes you need to care about.


Know the difference before you write an offer
Getting your offer accepted feels like the finish line - but escrow is where the real work begins.
Know your numbers before you fall in love!

Here is how they actually compare

What makes a school good?
As a Bay Area native and San Jose State graduate, Veronica has leveraged her Bachelor’s degree in Business and experience in sales to consistently outperform the market and generate the most profitable results for her clients. With a commitment to excellence and a deeply rooted passion for real estate.
Get In Touch With Veronica Peter
900 Main St., #101 Pleasanton, CA 94566